Is the Economy Really in Trouble? A Debate

¯\_(ツ)_/¯ :

But right now I’m stuck. I have no idea how the United States economy is doing. And the closer I look at the data, the more contradictory it looks.

• • •

I’ve tried several times in the last few weeks to convince myself that one of those stories is correct, but just can’t decide between them. And because The New York Times is not fond of headlines that include the “shruggie” emoticon (for the uninitiated, that would be ¯\_(ツ)_/¯), I have held off writing anything.


Why am I telling you all this? Because sometimes the most accurate portrayal of a situation revolves around uncertainty — and because we journalists aren’t always honest about that. This is my effort to be a little more honest.
→ The New York Times

How Repo Works


An interesting and simple explanation on how repurchase-agreements work :

In a repo transaction one institution (the lender) agrees to buy an asset from another institution (the borrower) and sell the asset back to the borrower at a pre-agreed price on a pre-agreed future date (a day, a week or more). The lender takes a fee (repo interest rate payment) for ‘buying’ the asset in question and can sell the asset in the case that the borrower does not live up to the promise to repurchase it. The fundamental purpose of this circular transaction is to lend and borrow funds (and, in some cases, securities). While financial institutions use it to raise finance, central banks use it in monetary policy.

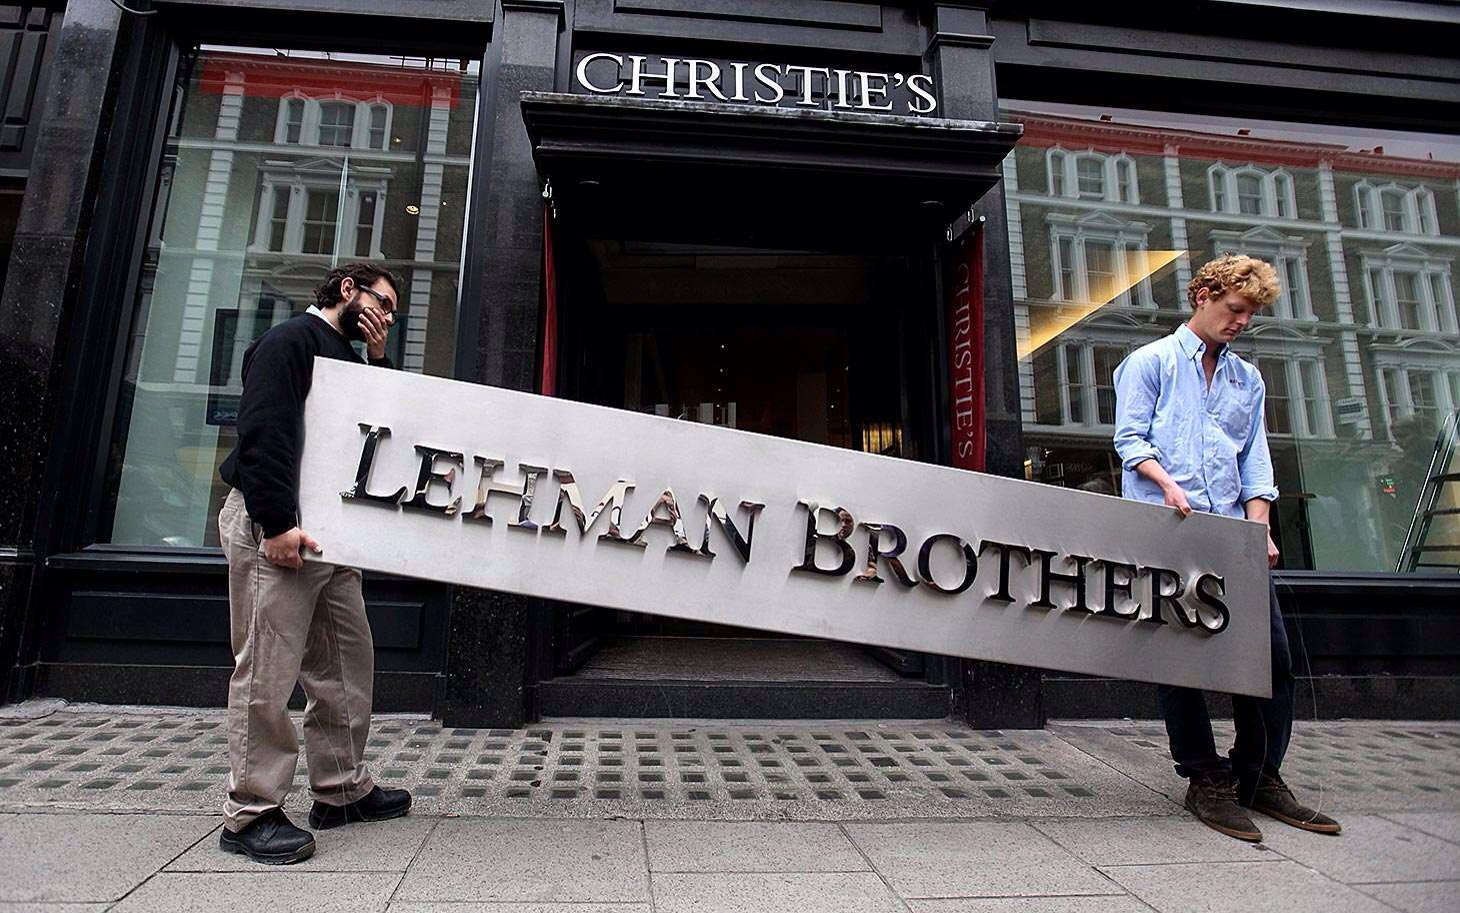
The very same technique Lehman Brothers used and perfected through the now infamous Repo 105. Read further for the NPR account :

Everybody knows the bank isn’t really selling the bond to the big company — it’s really borrowing money. So under accounting rules, the assets a bank uses in repo deals stay on the bank’s balance sheet.

But when Lehman Brothers wanted to make it look like it wasn’t borrowing so much money, the company used a special technique to get around this rule. It did repo deals where it took slightly less cash than the asset was worth.

→ Naked Capitalism

The Legend Of The Donald

While the King may not be dead yet, long live the King :

The Donald’s reputation for building castles had inspired many apprentices who sought to learn at his feet. When apprentices displeased him, however, he would elucidate their inferior qualities and then place them inside a cannon. As an underling fired it, the Donald would declare, “You’re fired—out of a cannon.”

This phrase had long delighted the people, as had the other phrases he habitually employed, but the people were in a quandary. Experts in kingship had assured them that there was no harm in voting for the Donald, as he did not stand a real chance of ascending to the throne; yet these scholars were now saying, tarry, it might happen, and imagine what our realm would actually look like if we had a King the Donald!

→ The New Yorker

The Fable Of The Unicorn

Yet in other ways Theranos evokes a central theme in today’s tech industry: start-ups which promise to disrupt lucrative businesses and become valued on the basis of fantasies about their potential, rather than present reality. Investors are so keen to get a piece of any sexy-sounding startup that they lap up entrepreneurs’ hype—and anyone who asks awkward questions risks being cut out of the funding round in favour of someone more trusting.

All this helps to explain the inflation of valuations among unlisted technology companies. Today there are 142 unicorns, more than three times as many as in 2013. Many of them are growing quickly. But in terms of reaching profitability, they are often far behind the stockmarket-listed competitors they are seeking to displace, and thus are burning through cash. Theranos, for example, is not believed to have any significant revenues or profits, yet it is valued about as highly as Quest Diagnostics, a listed laboratory company, which achieved $7.4 billion in revenues and nearly $600m in net profits in 2014.

→ The Economist

Should You Be Allowed to Invest in a Lawsuit?

This new form of lawsuit funding is called litigation finance. It lies at the crossroads of two Anglo-American tendencies. The first is our litigious side, in which we celebrate our equality before the law by dragging those who have wronged us before a judge. The second is our ingenious mercantilism, as demonstrated by our penchant for turning everything from church raffles to mortgages into marketable securities to be chopped up, bundled and resold. Like the celebrity bonds backed by royalties and popularized by David Bowie during the 1990s, litigation finance represents the expansion of securitization into hitherto virgin territory.

→ The New York Times Magazine