Activision to Buy Candy Crush’s King for $5.9bn

John Gruber on the acquisition :

They were only going to pay $1 billion, but then they got stuck on a couple of levels, bought some gold bars, and, well, here they are.

More to follow later today (maybe), but as a reminder, here’s a poignant statement from an indie developer allegedly ripped off by King.com :

Congratulations! You win! I created my game CandySwipe in memory of my late mother who passed away at an early age of 62 of leukemia. I released CandySwipe in 2010 five months after she passed and I made it because she always liked these sorts of games. In fact, if you beat the full version of the android game, you will still get the message saying “…the game was made in memory of my mother, Layla…” I created this game for warmhearted people like her and to help support my family, wife and two boys 10 and 4.

I have never downloaded nor played to any of their apps, I find them dumb and unaesthetic. In light of the previous statement I could only encourage you to remove them. 

Plus, I see mostly bored housewives or early teens playing Candy Crush, which makes the price of the acquisition even more insane. They are not real gamers like the core business of Activision-Blizzard, which is used to produce highly polished and immersive games. But I guess that’s where part of the money is to be made anyway and that’s sad. 
→ Financial Times

How Repo Works


An interesting and simple explanation on how repurchase-agreements work :

In a repo transaction one institution (the lender) agrees to buy an asset from another institution (the borrower) and sell the asset back to the borrower at a pre-agreed price on a pre-agreed future date (a day, a week or more). The lender takes a fee (repo interest rate payment) for ‘buying’ the asset in question and can sell the asset in the case that the borrower does not live up to the promise to repurchase it. The fundamental purpose of this circular transaction is to lend and borrow funds (and, in some cases, securities). While financial institutions use it to raise finance, central banks use it in monetary policy.

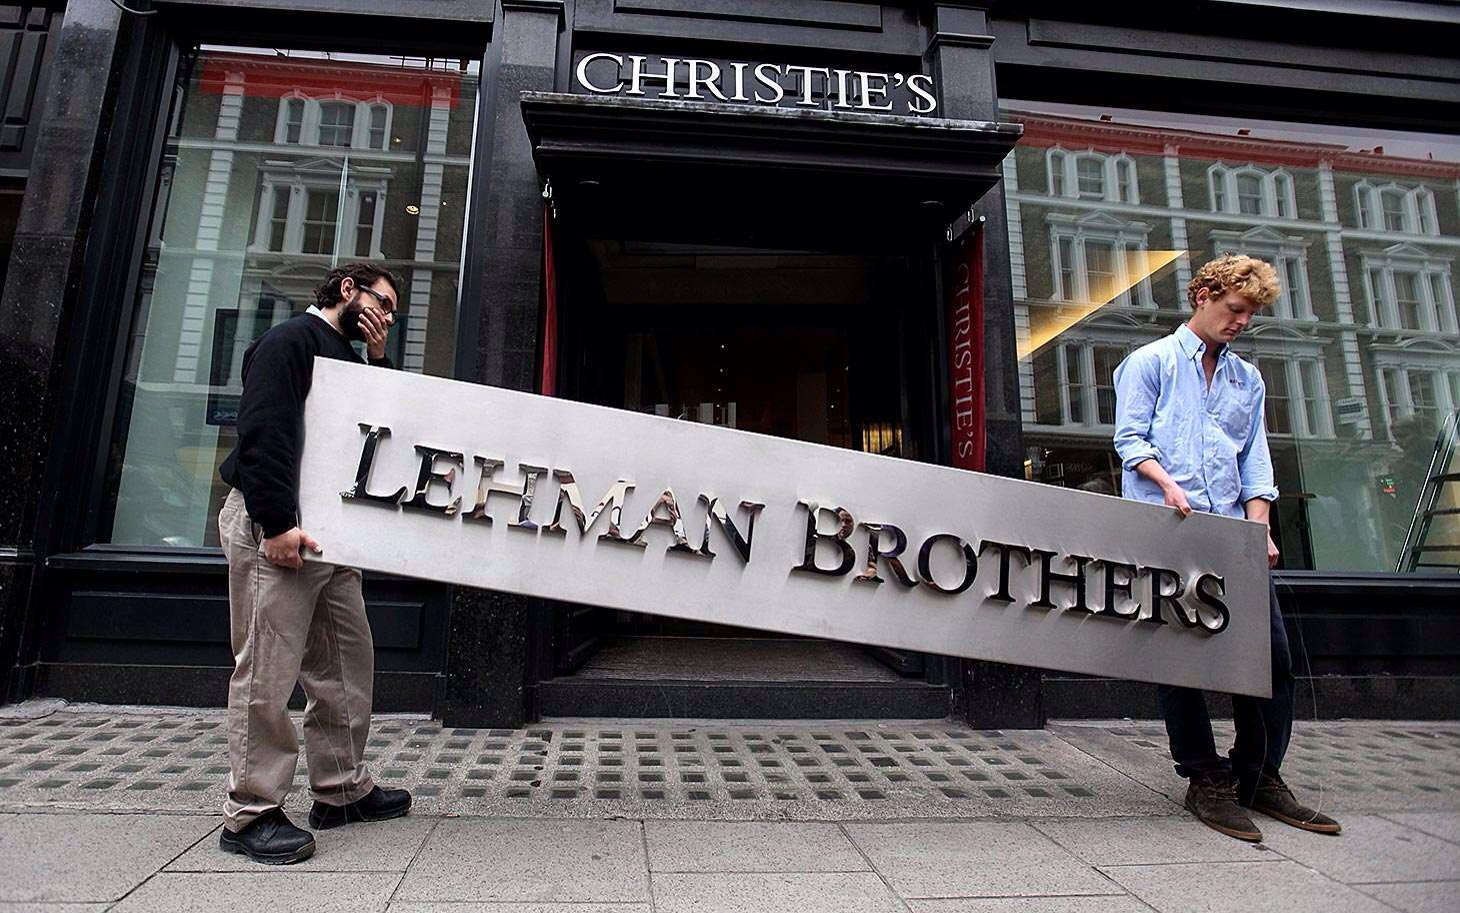
The very same technique Lehman Brothers used and perfected through the now infamous Repo 105. Read further for the NPR account :

Everybody knows the bank isn’t really selling the bond to the big company — it’s really borrowing money. So under accounting rules, the assets a bank uses in repo deals stay on the bank’s balance sheet.

But when Lehman Brothers wanted to make it look like it wasn’t borrowing so much money, the company used a special technique to get around this rule. It did repo deals where it took slightly less cash than the asset was worth.

→ Naked Capitalism

The Fable Of The Unicorn

Yet in other ways Theranos evokes a central theme in today’s tech industry: start-ups which promise to disrupt lucrative businesses and become valued on the basis of fantasies about their potential, rather than present reality. Investors are so keen to get a piece of any sexy-sounding startup that they lap up entrepreneurs’ hype—and anyone who asks awkward questions risks being cut out of the funding round in favour of someone more trusting.

All this helps to explain the inflation of valuations among unlisted technology companies. Today there are 142 unicorns, more than three times as many as in 2013. Many of them are growing quickly. But in terms of reaching profitability, they are often far behind the stockmarket-listed competitors they are seeking to displace, and thus are burning through cash. Theranos, for example, is not believed to have any significant revenues or profits, yet it is valued about as highly as Quest Diagnostics, a listed laboratory company, which achieved $7.4 billion in revenues and nearly $600m in net profits in 2014.

→ The Economist

Lunch with the FT: Ben Bernanke

Martin Wolf :

I ask him whether he is confident that the improvement in the resilience of the banks is adequate. “It’s a fool’s game to predict that everything is going to be fine, because either it is fine, in which case nobody remembers your prediction, or something happens, and then … ” They remember your prediction, I interject.

Bernanke continues: “My mentor, Dale Jorgenson [of Harvard], used to say — and Larry Summers used to say this, too — that, ‘If you never miss a plane, you’re spending too much time in airports.’ If you absolutely rule out any possibility of any kind of financial crisis, then probably you’re reducing risk too much, in terms of the growth and innovation in the economy.”

→ Financial Times

The Trouble With Financial Bubbles

Follow-up on macro-microprudential policies :

Industrial quantities of research, analysis, and debate have been devoted to the causes of the 2008 crisis and its consequences; so it seems odd that senior central bankers are still so sharply divided on the central issue of financial stability. All those days spent in secret conclave in Basel, drinking through the BIS’s legendary wine cellar, have apparently led to no consensus.

→ Project Syndicate