Agressive HFT And Institutional Trading Activity – Who Leads Market Crashes ?

Hallelujah, high-frequency traders didn’t short the market that much :

Our analysis of trading on August 24, 2015, shows that while there were bursts of aggressive HFT activity during the sell-off, it was the institutional activity, not the HFT activity that led and dominated the sell-off. Specifically, the events have appeared to unfold as follows: institutions would sell particular securities, creating acute selling pressure in the markets. Aggressive HFTs would then step in and sell the market further, but only for a relatively short period of time.
→ Traders Magazine

A Different Approach To VC

Fred Wilson :

I wrote this to my partner the other day. I’m not going to provide the context. It doesn’t matter. It could have been about almost anything in the startup sector right now.
“the biggest thing that is wrong with the startup sector right now is entrepreneurs and their teams are too focused on valuation and not enough focused on business fundamentals”

→ A VC

Risky Strategy Sinks Small Hedge

Follow-up on some less successful investment strategies by hedge-funds, to say the least :

The back-tested results for the Spruce Alpha fund may not have taken into account how markets and investors would react given the kind of circumstances that took place in August. The hypothetical results could have underestimated the fact that some E.T.F.s are used as trading instruments that big money managers move quickly in and out of in times of extreme market volatility.

In a disclaimer to its marketing materials, Spruce Alpha also noted some of the unreliability of back-tested returns. The hypothetical results “do not represent the results of actual trading” and “were achieved by means of the retroactive application of a hypothetical model that was designed with the benefit of hindsight and could be adjusted at will until desired or better performance results were achieved,” the disclaimer reads.

→ The New York Times

Markets : Can They Really Be Tamed ?

On computer-driven, automatic trading strategies :

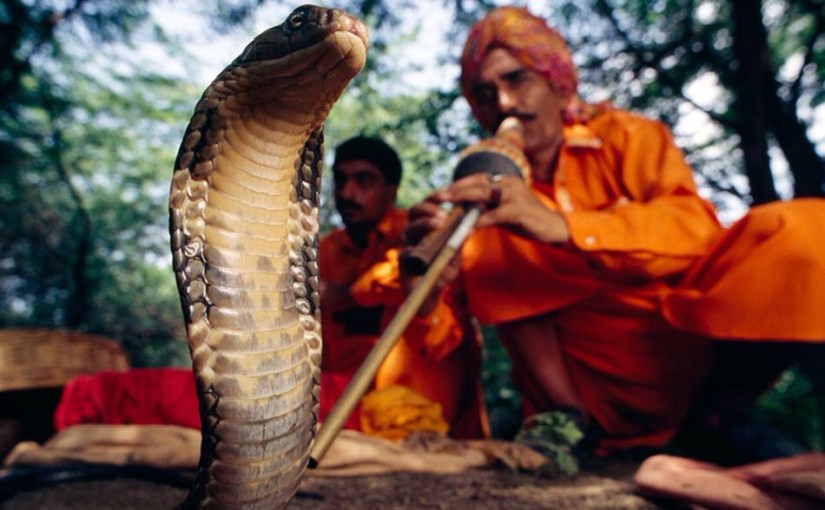
Cobras are revered in Indian culture, but the British Raj took a dimmer view of the poisonous snake. Officials promised a lucrative reward for every dead serpent — a scheme that, according to economic lore, backfired horribly.

Enterprising Indians began breeding cobras to collect the bounty, which forced the colonial government to abandon the plan. The frustrated breeders then released the worthless cobras, worsening the infestation. The story has never been fully confirmed by historians, but was seized on by German economist Horst Siebert, who in 2001 published The Cobra Effect on perverse incentives and unintended consequences. The book turned the anecdote into a potent example of how solutions to a problem can make it worse.

→ The Financial Times

The Free Market: It’s Like Uber, But for Everything

There is increasing speculation that Uber’s long-anticipated initial public offering could be valued at $100 billion, a value that has been created by undercutting the prices of traditional taxis and offering more and better service. If that’s how much wealth can be generated just by rediscovering the laws of economics in this one narrow area, think what could be accomplished if we do it for the economy as a whole.

It would be like Uber, but for everything.

→ The Federalist