The TCC avenue would clearly be a superior solution, and would allow Greece to stayin the Eurozone, while stimulating demand by increasing citizens’ purchasing power, reducing domestic labor costs, and significantly increasing GDP. This would also generate, in due course, higher gross tax receipts (which would offset the shortfall in euro fiscal revenue due to TCC issuance).
Who Is Saudi Arabia Really Targeting In Its Price War?
Follow-up on the previous article, this one from Arthur Berman for Naked Capitalism :
Prolonged low oil prices will prove that tight oil plays need at least $75 per barrel to break even. When oil prices recover to that level, only the best parts of the tight oil core areas will be competitive in the global market. As production declines from expensive tight oil, oil sand and ultra-deep-water plays, inexpensive Saudi oil will gain market share.
Saudi Arabia is not trying to crush tight oil plays, just the stupid money that funded the over-production of tight oil. Too much supply combined with weak demand created the present oil-price collapse. Saudi Arabia hopes to prolong low prices to benefit their long-term needs for market share and higher demand.
Why Oil Prices Came Down, And Won’t Anymore
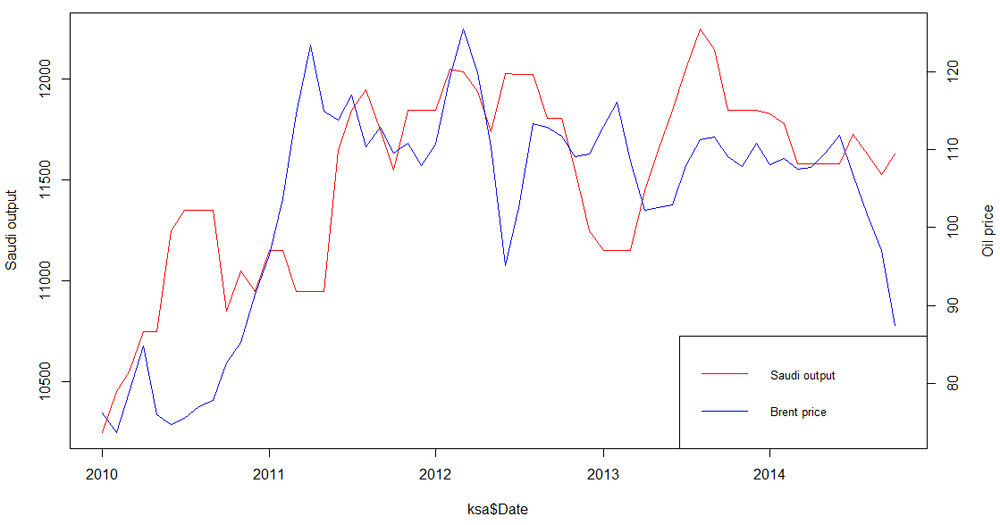 Historically, Saudi Arabia has played a stabilizing role in world oil prices, by adjusting its output to ensure global supply is stable. The above graph show how Saudi output increased to lower prices when they were high, and vice versa. However, since July, the Saudis have not responded to newly low oil prices by decreasing output. In fact, the Kingdom have insisted that they would rather bear lower oil prices than decrease their market share (read: be squeezed out by shale).
Another Reason We Don’t Apply the 80-20 Rule
You’ll get one more reason by clicking the link down below :
The 80-20 rule sounds too good to be true. If 20% of inputs are so much more important than the others, why don’t we just concentrate on those? In an earlier post, I gave four reasons. These were:
- We don’t look for 80/20 payoffs. We don’t see 80/20 rules because we don’t think to look for them.
- We’re not clear about criteria for success. You can’t concentrate your efforts on the 20% with the biggest returns until you’re clear on how you measure returns.
- We’re unclear how inputs relate to outputs. It may be hard to predict what the most productive activities will be.
- We enjoy less productive activities more than more productive ones. We concentrate on what’s fun rather than what’s effective.
The IMF’s Big Greek Mistake
Ultimately, the authorities’ approach merely replaced one problem with another: IMF and official European loans were used to repay private creditors. Thus, despite a belated restructuring in 2012, Greece’s obligations remain unbearable — only now they are owed almost entirely to official creditors.

