How Repo Works


An interesting and simple explanation on how repurchase-agreements work :

In a repo transaction one institution (the lender) agrees to buy an asset from another institution (the borrower) and sell the asset back to the borrower at a pre-agreed price on a pre-agreed future date (a day, a week or more). The lender takes a fee (repo interest rate payment) for ‘buying’ the asset in question and can sell the asset in the case that the borrower does not live up to the promise to repurchase it. The fundamental purpose of this circular transaction is to lend and borrow funds (and, in some cases, securities). While financial institutions use it to raise finance, central banks use it in monetary policy.

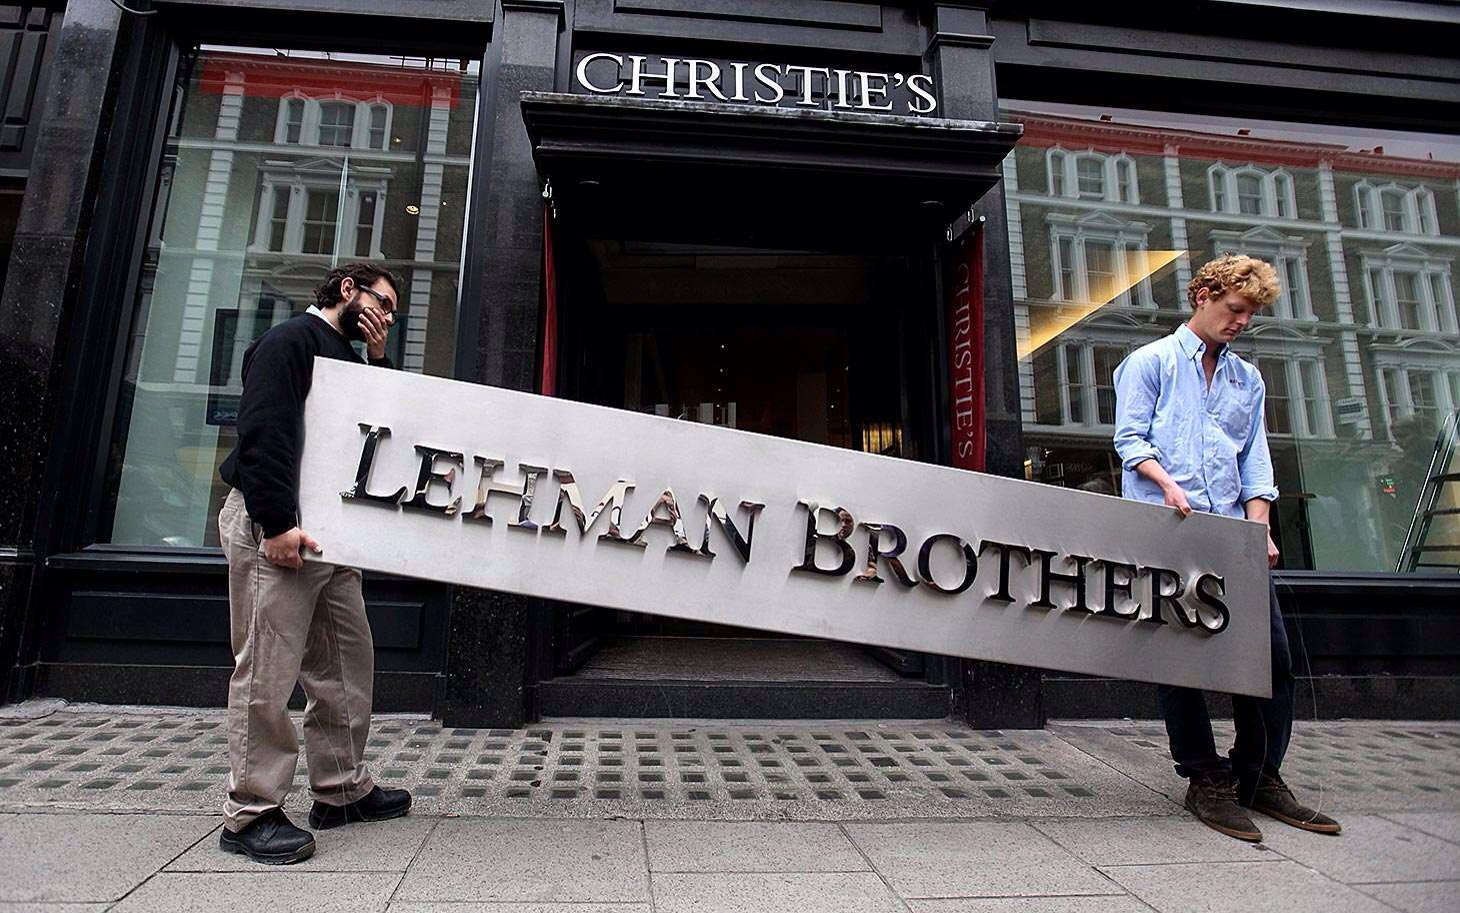
The very same technique Lehman Brothers used and perfected through the now infamous Repo 105. Read further for the NPR account :

Everybody knows the bank isn’t really selling the bond to the big company — it’s really borrowing money. So under accounting rules, the assets a bank uses in repo deals stay on the bank’s balance sheet.

But when Lehman Brothers wanted to make it look like it wasn’t borrowing so much money, the company used a special technique to get around this rule. It did repo deals where it took slightly less cash than the asset was worth.

→ Naked Capitalism

The Fable Of The Unicorn

Yet in other ways Theranos evokes a central theme in today’s tech industry: start-ups which promise to disrupt lucrative businesses and become valued on the basis of fantasies about their potential, rather than present reality. Investors are so keen to get a piece of any sexy-sounding startup that they lap up entrepreneurs’ hype—and anyone who asks awkward questions risks being cut out of the funding round in favour of someone more trusting.

All this helps to explain the inflation of valuations among unlisted technology companies. Today there are 142 unicorns, more than three times as many as in 2013. Many of them are growing quickly. But in terms of reaching profitability, they are often far behind the stockmarket-listed competitors they are seeking to displace, and thus are burning through cash. Theranos, for example, is not believed to have any significant revenues or profits, yet it is valued about as highly as Quest Diagnostics, a listed laboratory company, which achieved $7.4 billion in revenues and nearly $600m in net profits in 2014.

→ The Economist

Should You Be Allowed to Invest in a Lawsuit?

This new form of lawsuit funding is called litigation finance. It lies at the crossroads of two Anglo-American tendencies. The first is our litigious side, in which we celebrate our equality before the law by dragging those who have wronged us before a judge. The second is our ingenious mercantilism, as demonstrated by our penchant for turning everything from church raffles to mortgages into marketable securities to be chopped up, bundled and resold. Like the celebrity bonds backed by royalties and popularized by David Bowie during the 1990s, litigation finance represents the expansion of securitization into hitherto virgin territory.

→ The New York Times Magazine

Lunch with the FT: Ben Bernanke

Martin Wolf :

I ask him whether he is confident that the improvement in the resilience of the banks is adequate. “It’s a fool’s game to predict that everything is going to be fine, because either it is fine, in which case nobody remembers your prediction, or something happens, and then … ” They remember your prediction, I interject.

Bernanke continues: “My mentor, Dale Jorgenson [of Harvard], used to say — and Larry Summers used to say this, too — that, ‘If you never miss a plane, you’re spending too much time in airports.’ If you absolutely rule out any possibility of any kind of financial crisis, then probably you’re reducing risk too much, in terms of the growth and innovation in the economy.”

→ Financial Times

China in Africa: A Modern Story of Colonization?

However China’s increased presence in East Africa has gradually raised concerns about the economic development of these countries as well as the environmental and social sustainability of their natural resources; what remains unclear is whether China’s recent FDI in East Africa has any real intention in helping to promote economic growth and development in these countries. In recent times, China has undertaken multiple investments in sub Saharan Africa that most people believe is due to China’s search for natural resources to feed its industrial output. But it has not always been the case.

→ Economonitor